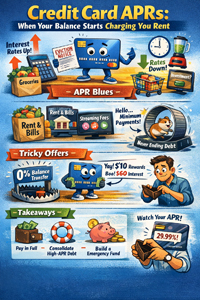
 Credit card APRs (Annual Percentage Rates) shape how we borrow, spend, and plan, and like that one friend who brings a calculator to brunch, they quietly ruin the vibe. APRs determine the cost of carrying a balance: interest compounds daily, so even a “small” rate can snowball faster than your online shopping cart at 2 a.m.
When rates rise, credit card APRs usually follow. Suddenly, your balance starts charging you rent. New offers get pricier, variable rates climb, and budgets feel tighter. When rates fall, borrowing feels cheaper, and that “nice to have” blender magically becomes a “long-term investment.”
Higher APRs discourage carrying balances… in theory. In reality, interest charges compete with essentials like groceries, rent, and utilities, plus those streaming services you “totally use.” This squeeze can lead to cutting back, buying cheaper alternatives, or making minimum payments, which is basically putting your debt on a treadmill that never turns off.
For lower-income households or those with subprime credit, the impact hits harder. They’re more likely to rely on high-APR products and have less cushion. It’s like being told to stay calm while juggling flaming swords.
Promotional offers add another twist. A 0% APR balance transfer can feel like a fresh start, but miss the promo window and the rate jumps fast. Rewards cards can still be worth it if you pay in full, but carrying a balance wipes out those perks quickly. Congrats, you earned $10… and paid $60 in interest.
There are broader effects too. Higher APRs can slow consumer spending, which drags on economic growth. Lenders may tighten standards as delinquencies rise, making credit harder to access. Translation: everyone spends less, and the economy feels it.
Moral of the story:
Practical takeaways include paying balances in full when possible; comparing balance transfer offers and fees; considering consolidating high-APR debt; and building an emergency fund so your credit card isn’t your backup plan. Finally, keep an eye on your APR, because this is one bill that never forgets.