 Inflation quietly reshapes the value of your investments, like that sneaky roommate who uses your milk and never replaces it. At its simplest, inflation is the rising cost of goods and services over time, meaning a dollar today buys less tomorrow (and your future self will judge your past self for wearing those 2010s investing pants).
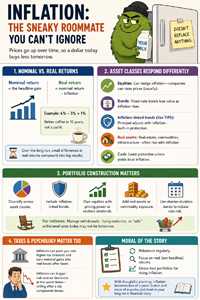
Separate nominal vs. real returns. Nominal return is the headline gain; real return = nominal return − inflation. If your savings earn 4% but inflation is 3%, your real return is only 1%, enough to buy a slightly larger coffee in 10 years, but not a yacht. Over long horizons, small differences compound: a consistent 1% real return doubles purchasing power much more slowly than a 3% real return.
Asset classes respond differently. Equities can hedge inflation because companies can raise prices, unless customers stage a mass rebellion. High inflation plus rising rates can squeeze margins and hurt growth stocks. Bonds are vulnerable: fixed-rate bonds lose value as inflation rises, while inflation-linked bonds (like TIPS) adjust principal and act like a seatbelt. Real assets, real estate, commodities, infrastructure, often track inflation since rents and prices rise. Cash and money-market holdings are the least protective unless yields exceed inflation.
Portfolio construction matters. Diversify across asset classes: include inflation-linked bonds, equities with pricing power or resilient dividends, and consider real assets or commodity exposure. Shorter-duration bonds reduce interest-rate sensitivity. For retirees, manage withdrawals: inflation raises living costs, so withdrawal rates that looked safe may become optimistic.
Inflation can push taxpayers into higher brackets and turn nominal gains into real losses after taxes. Psychologically, inflation can trigger risk-averse behavior at the worst times, selling after a dip, which compounds losses.
Moral of the story:
Rebalance regularly, monitor real (not headline) returns, and stress-test portfolios for rising inflation scenarios. With thoughtful planning, inflation becomes less of a panic button and more of a quirky plot twist in your long-term financial story.